Private Label Across Europe: 2024 Figures Show Another Successful Year
Europe's private labels: a growing force in retail
Tesco continues to dominate UK market; Marks & Spencer deemed purest PL player

In the UK market, the traditional “Big Four” retail players, Tesco, Sainsbury’s, Asda and Morrisons, have long since given space to newcomers Aldi and Lidl. In fact, where 20 years ago, Aldi and Lidl combined held 4% of the market, their market share now is 19%. The new top 4 sees Tesco on top with a 28% market share, followed by Sainsbury’s with 15%, Aldi accounts for 10% and Lidl stands at 9%.

This became clear at PLMA’s Private Label Summit in Manchester at the end of October. Adam Leyland of trade magazine, The Grocer, painted a picture of the UK grocery landscape. In answer to the question whether the UK is still the private label exemplar for the rest of the world, Leyland offered an “unquestionably yes.”

Marks & Spencer are the purest private label retailer in the UK, with a 96.7% own label spend share. M&S is expanding its store network and wants to grow to 420 M&S food halls by 2028. Discounters follow the ranking with Aldi scoring 91.6% and Lidl an 81.9 % own label spend share.

More than 150 Summit participants experienced UK retailers and their private label programmes firsthand during the extensive guided tour that touched on 6 retail stores in Manchester. At the conclusion of the tours, there was a networking reception at Manchester United’s Old Trafford Stadium overlooking one of Britain's most famous pitches.
Midlife shoppers present 'loyalty' challenge for grocery retailers and brands

Shoppers aged 45 to 54 are the least loyal to grocery brands, as financial pressures increasingly influence purchasing decisions, according to IGD.

IGD’s latest research highlights how the rising cost of living is affecting different age groups, with mid-life consumers facing particularly tight household budgets. Just 35% of 45 to 54-year-olds consider themselves financially comfortable, while housing costs and household bills account for 49% of their monthly expenditure.

The findings also reveal differences in loyalty across multiple generations. 

Retailer loyalty is lowest among 55 to 64-year-olds, at 55%, while brand loyalty reaches its lowest level among 45 to 54-year-olds, at 51%.

For retailers and suppliers, the research suggests that demonstrating value is becoming increasingly important for retaining existing customers, rather than simply attracting new ones.

However, value does not necessarily mean choosing the cheapest option. Consumers aged 45 to 64 are particularly conscious of spending but continue to weigh price against quality. Product longevity, reduced waste, freshness and consistent availability are all becoming important considerations.

IGD head of shopper insight Caroline Young said many mid-life consumers are part of the ‘sandwich generation’, managing financial responsibilities towards both children and ageing parents.

For the grocery industry, this underlines the importance of offering clear value and giving shoppers confidence that their purchases justify the price.

French consumers face a cautious Christmas as holiday-related spending comes under pressure

French consumers are approaching the 2026 holiday season with caution, as economic uncertainty and pressure on household budgets weigh on spending intentions. According to an exclusive LSA x YouGov survey, conducted on 7–8 September among 1,008 adults, 58% of the French population remain pessimistic about the months ahead.

While 75% intend to celebrate Christmas, more than half (52%) expect the current economic climate to change their plans. Of these, 75% anticipate reducing their overall budget, while 26% plan to invite fewer guests and 19% expect to cut back on family travel. Value for money will remain a priority, with 72% intending to pay closer attention to promotions than last year.

The outlook for festive FMCG is consequently difficult to predict. According to Circana, festive food products, including foie gras and seasonal chocolates, recorded a 1.8% decline in value and a 3.6% fall in volume during the 2025 season. Sales in hypermarkets were particularly challenging, with value down 3.9%.

Looking ahead, 51% of French consumers expect their festive food budget to remain stable, while 27% anticipate spending less. Circana identifies two possible scenarios for the coming season: modest growth if consumers continue to treat themselves, or declining volumes as households become more cautious with their spending. The coming weeks should provide a clearer indication of which trend will prevail.

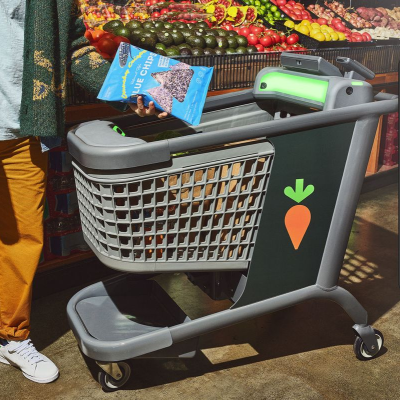
Smart shopping carts: retailers face a difficult choice after Instacart exit

Instacart’s decision to discontinue its Caper smart carts leaves supermarket groups facing a rethink. Carrefour Belgium’s trial is now on hold, while Morrisons is ending its smart cart pilot. Other retailers using Caper, including US Kroger, Wakefern, Schnucks and Australian Coles, will need clarity on future servicing and support as the business winds down by Q2 2027.

The withdrawal does not mean the technology failed with shoppers. Instacart reported Net Promoter Scores above 70 at established locations and claimed double-digit basket growth across retail partners. An on-screen “Got everything?” prompt reportedly lifted basket size by almost one percentage point. Separately, a 2026 Bayes Business School study of 12,418 shopping sessions at a German supermarket found smart-cart users spent 32% more and bought 25% more items on average.

The problem was scale, not necessarily shopper appeal. Instacart said retailer adoption had not grown quickly enough to justify continued investment. Smart carts require hardware, maintenance and systems integration; retailers must persuade customers to use them and demonstrate returns across stores.

Alternatives remain. Amazon continues to develop its Dash Cart, while Veeve, Shopic and Israel-based Cust2Mate offer smart-cart or retrofit solutions. Carrefour already works with Cust2Mate in France and Israel, and Belgium’s Colruyt has developed its own Smart Cart. These options differ in functionality and availability, so they are not automatic replacements.

So, the end of Caper does not mean the end of smart shopping carts. Instacart’s withdrawal does, however, highlight the challenges of rolling out new technology across large supermarket networks, where investment, maintenance and customer adoption all need to add up commercially. 

Cyberattacks expose retailers’ vulnerability

Cyberattacks on supermarkets are posing new threats, with recent incidents showing that digital interference can have consequences far beyond websites, payment systems and customer data. 

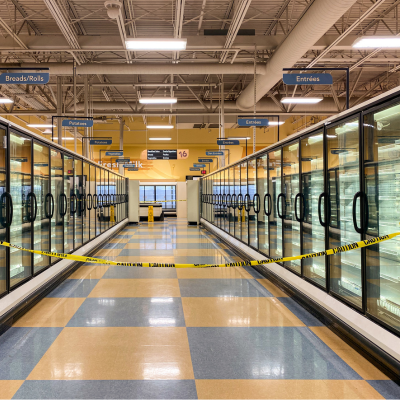
On 2 November, supermarkets in Belgium, Luxembourg, Sweden and Estonia reported overnight refrigeration problems. Delhaize confirmed an IT incident affecting cooling systems in dozens of stores. Colruyt reported five affected shops, while Sweden’s ICA and Coop also experienced incidents. Investigations are ongoing, and there is no confirmation that the attacks are connected.

The incidents follow a major attack in France in October, when hackers manipulated connected refrigeration controllers at hundreds of supermarkets, forcing units into defrost mode. Temperatures reached 50°C, resulting in spoiled stock, fires at some locations and damage estimated in the tens of millions of euros.

The disruption is not limited to refrigeration. In October, a cyber incident at Ahold Delhaize led to precautionary shutdowns affecting websites, apps, online orders and logistics across several European and US banners. The 2025 attacks on M&S and Co-op, alongside the ransomware incident at supply-chain technology provider Blue Yonder, offer further reminders of how quickly disruption can spread between businesses.

Behind these incidents is a growing dependence on connected systems throughout the food chain. Refrigeration, warehouse management, production equipment and building controls are increasingly networked, sometimes with remote access for external contractors. These connections can become entry points when software is outdated, passwords are weak or systems are poorly separated from corporate networks.

The consequences are tangible: lost stock, interrupted deliveries, production delays, food-safety concerns and damaged customer confidence. As more physical operations depend on connected technology, protecting those systems is becoming as important as securing company data. Cyber resilience is becoming part of keeping shelves stocked and supply chains moving, not simply an IT concern.

Eurelec brings European pricing practices to the fore

Ten years after its creation, European buying alliance Eurelec is setting its sights on greater transparency in cross-border pricing. As the partnership between E.Leclerc, Rewe and Ahold Delhaize enters its second decade, understanding the differences in commercial conditions between national markets is becoming a central part of its agenda.

Operating across eight countries, Eurelec recorded purchasing volumes of €13.39bn in 2025, up 8.3%, and expects to approach €15bn in 2026. It now works with 46 major multinational suppliers, giving it a broad view of pricing practices across several European markets.

The alliance argues that purchasing prices for identical products, sometimes manufactured in the same factory, can vary by as much as 40% between countries. While differences in local costs, market conditions and commercial strategies may explain some of this variation, Eurelec believes that greater transparency is needed to understand the reasons behind it.

Territorial supply restrictions are another focus. Country-specific distribution arrangements can limit access to purchasing conditions available in neighbouring markets, raising questions about the practical functioning of the EU Single Market.

The debate also highlights the regulatory complexity of European trade. Eurelec's ongoing disagreement with French authorities over the application of national commercial law to contracts negotiated in Belgium illustrates how national legislation can continue to complicate cross-border business, despite decades of European market integration.

More broadly, the situation underlines a persistent contradiction at the heart of the European grocery market: retailers and suppliers increasingly operate across borders, yet commercial conditions and regulatory frameworks remain largely shaped by individual national markets.

Aldi Belgium steps up app-based promotions, puts private labels in the spotlight

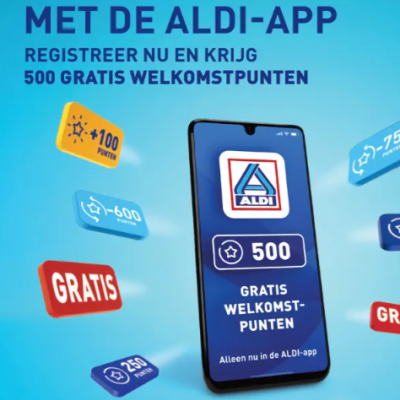
Aldi Belgium is strengthening its digital loyalty strategy by rolling out around ten exclusive promotions each week for app users, placing fresh food and private label products at the heart of the initiative.

The additional offers, which run alongside Aldi’s regular weekly specials, cover categories including fresh fruit and vegetables, meat, fish and the retailer’s own brand range. Discounts are automatically applied at checkout when customers scan their Aldi app, making the savings immediate and requiring no additional steps.

The move builds on Aldi Belgium’s loyalty programme, introduced across its stores last year. Members can collect points to exchange for free products or further discounts. According to Aldi, the programme has gained traction, with increasing numbers of shoppers regularly using the app.

The strategy also reflects changing consumer expectations. Research conducted by iVOX on behalf of Aldi found that three-quarters of Belgian consumers primarily expect immediate discounts at checkout from loyalty programmes. Aldi’s latest initiative directly responds to this demand, while providing an additional incentive for shoppers to engage digitally.

Interestingly, Belgium serves as the exclusive testing ground for Aldi's app-based discounts. This contrasts with Aldi’s approach in almost all other markets, including Germany, the UK and Australia, where the discounter explicitly rejects loyalty schemes and treats them publicly as a marketing enemy.

CSR Retail Index 2026: Carrefour and Jerónimo Martins lead the pack


Carrefour and Jerónimo Martins share the top spot in the 2026 CSR Retail Index, each scoring 13.3 out of 20, according to the report produced by ESSEC Business School’s Consumer Goods Chair and consulting firm BDO.

The second edition assesses the sustainability performance of 12 European retailers using 16 quantitative ESG indicators drawn from the European Sustainability Reporting Standards (ESRS). The indicators cover areas including Scope 1, 2 and 3 greenhouse-gas emissions, waste, employee turnover, disability representation, gender pay gaps and sustainability-linked remuneration. Environmental performance accounts for 42% of the score, social factors for 35% and governance for 23%.

Carrefour retained its leading position, improving its score by 0.5 points, with governance identified as a particular strength. Jerónimo Martins climbed two places ending up in a tie with Carrefour, gaining 0.8 points through more balanced progress across environmental, social and governance measures.

Colruyt entered the index in third place, while Auchan (7th) recorded the largest improvement, gaining 1.9 points. Its progress was linked to lower Scope 3 emissions, a reduction in its gender pay gap from 18% to 7%, and sustainability targets being tied to 20% of annual incentives.

At the other end of the scale, Sonae fell from fourth to ninth after a 1.2-point decline in environmental performance. By individual pillars, Carrefour led governance, Jerónimo Martins social performance, and Ahold Delhaize environmental performance.

The companies assessed in the 2026 CSR Retail Index are retailers subject to the EU reporting obligation, as well as retailers who anticipate the obligation by publishing an sustainability report compliant with the ESRS.